"National Preparedness Month — and the possibility of a historically strong El Niño — are important reminders that preparation should happen before severe weather enters the forecast," said Bobby Massey, Head of Catastrophe Claims at Farmers®. "Our catastrophe claims teams see how quickly storms can disrupt lives, but also how preparation can support recovery. Reviewing coverage and deductibles, documenting property and addressing risks around the home now can make a meaningful difference after a loss."
What is El Niño
El Niño is a natural climate pattern that develops when parts of the tropical Pacific Ocean become much warmer than usual. That heat can shift the jet stream, which helps steer storms and weather patterns across the United States. Impacts vary by region, but a strong El Niño can bring heavy rain, flooding, powerful storms, landslides and dangerous winter weather—conditions that can damage property, close roads, cause power outages and disrupt daily life.
El Niño typically occurs every two to seven years and can last up to 12 months. The most recent event developed in 2023 and ended in 2024.
Why NOAA says this El Niño could become historically strong
According to NOAA1:
- This El Niño will be unusually powerful because Pacific Ocean temperatures are already well above normal and are forecast to keep rising.
- There is a greater than 90% chance this El Niño will become very strong during fall and winter 2026-27.
- There's also a 69% chance it could exceed every El Niño measured since 1950.
- A stronger event can increase the chance of typical El Niño weather patterns, but it does not guarantee that every community will experience severe weather.
A powerful El Niño may increase the threat of heavy rain and flooding
Flood risk deserves particular attention because flood damage is typically not covered under a standard homeowners or business insurance policy. Many flood policies also include a waiting period before coverage takes effect, so coverage purchased when heavy rain or flooding is imminent may not apply to the approaching event.
"A flood can be devastating for a family or business," said Jeff Hinesly, Flood Director at Farmers. "Discovering afterward that the damage is not covered can make an already difficult situation even harder. Flood insurance cannot prevent the emotional toll of a disaster, but it can provide important financial support as homeowners and business owners begin to recover. That is why people should assess their flood risk and explore coverage options before severe weather is on the way."
El Niño's impacts may extend beyond winter
- Spring: In areas that receive increased rain or snow, added moisture may fuel more grass, brush and other vegetation in the spring.
- Summer: If that growth later dries out during hot, dry weather, it can provide additional fuel for wildfires. Regional conditions vary, so a wetter winter does not guarantee greater wildfire activity—but it may shape risks well into the warmer months.
"This year has already brought significant wildfire activity across the country, underscoring how quickly conditions can threaten homes and communities," said Massey. "With a potentially historic El Niño ahead, the risks may continue to evolve well beyond fall and winter. Preparing now—and staying alert as local conditions change—can help households and communities reduce risk in the months ahead."
Key preparedness actions
No checklist can address every risk, but Farmers claims experience points to eight checks that can help households prepare financially and reduce potential property damage before severe weather threatens.
- Confirm roof information. Roof age and condition may affect available coverage, settlement terms and claim outcomes, depending on the policy. Policy information should be updated after a roof replacement.
- Review dwelling coverage. A home's purchase price and market value are not necessarily the same as its reconstruction cost after a disaster. Labor, materials, permits and debris removal can significantly increase rebuilding expenses. Regularly reviewing dwelling coverage can help policy limits reflect current reconstruction costs.
- Understand flood risk. Standard homeowners insurance typically does not cover flood damage. A separate flood policy may be needed to protect a home from rising water. Because flood policies written through the National Flood Insurance Program (NFIP) have limits on the amount of coverage that can be purchased, speaking with an insurance professional about excess or private flood coverage could help consumers cover the full value of their property.
- Know the deductibles. A deductible is the amount a policyholder pays before insurance applies. Understanding the amount can help households plan for costs after a loss.
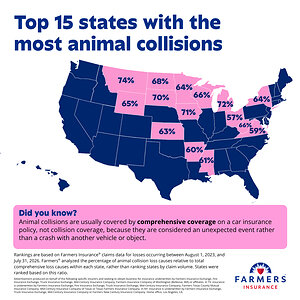
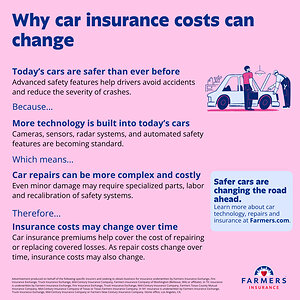
- Review car insurance. Comprehensive car coverage may help pay to repair or replace a car damaged by flooding, hail, falling objects or other weather-related events, subject to policy terms and deductibles.
- Clear gutters, drains and downspouts. Removing leaves and debris helps water drain away from a home instead of backing up near the foundation.
- Create a home inventory. Photos or video of each room, valuables and major purchases can help document losses. Model and serial numbers provide additional detail for items that may need to be replaced.
- Review additional living expense coverage. If a home becomes uninhabitable after a covered loss, this coverage may help pay for temporary housing and other increased living expenses. Policyholders should understand what their policy provides before a storm.
Helping communities prepare, respond and recover
Farmers supports nonprofit organizations working across the disaster lifecycle, helping communities prepare, respond and recover. Organizations include Strongward, which advances resilience and long-term recovery; Operation BBQ Relief, which serves meals to disaster-affected communities and first responders; Project:Camp, which provides safe spaces for children after disasters; and the American Red Cross, which delivers shelter, food and emergency assistance nationwide.
"Recovery is stronger when communities have support before, during and after a disaster," said Massey. "These sponsorships extend preparedness beyond individual households by helping deliver practical assistance when communities need it most."
Prepare before severe weather is in the forecast
To help consumers better understand severe-weather preparedness and related insurance considerations, Farmers offers a Hurricane Season Insurance Guide for Homeowners and Business Owners, including practical steps that may also be useful when preparing for heavy rain, flooding and other storm-related risks.
With El Niño expected to strengthen through the end of the year, Farmers encourages households and businesses to review coverage, address property risks and make preparedness plans before severe weather enters the forecast.
Source:
1CLIMATE PREDICTION CENTER/NCEP/NWS; EL NIÑO/SOUTHERN OSCILLATION (ENSO) DIAGNOSTIC DISCUSSION; https://www.cpc.ncep.noaa.gov/products/analysis_monitoring/enso_advisory/ensodisc.shtml
About Farmers Insurance
"Farmers Insurance®" and "Farmers®" are tradenames for a group of insurers providing insurance for automobiles, homes and small businesses and a wide range of other insurance and financial services products. Farmers Insurance Exchange, the largest of the three primary insurers that make up Farmers Insurance, is recognized as one of the largest U.S. businesses on the 2026 Fortune 500 list. For more information about Farmers Insurance, visit Farmers.com.
Advertisement produced on behalf of the following specific insurers and seeking to obtain business for insurance underwritten by Farmers Insurance Exchange, Fire Insurance Exchange, Truck Insurance Exchange, Mid-Century Insurance Company, Farmers Insurance Company of Washington (Bellevue, WA) or affiliates. In TX: insurance is underwritten by Farmers Insurance Exchange, Fire Insurance Exchange, Truck Insurance Exchange, Mid-Century Insurance Company, Farmers Texas County Mutual Insurance Company, Mid-Century Insurance Company of Texas or Texas Farmers Insurance Company. In NY: insurance is underwritten by Farmers Insurance Exchange, Truck Insurance Exchange, Mid-Century Insurance Company or Farmers New Century Insurance Company. Home office, Los Angeles, CA.
SOURCE Farmers Insurance



Share this article